UK's manufacturing orders improve for second consecutive month in Sept
Oct 06, 2026
United Kingdom manufacturing order books improved for a second consecutive month in September, while the decline in output volumes eased to a marginal pace, according to the Confederation of British Industry (CBI). Total order books were below 'normal' by the smallest margin since July 2023, and both total and export order books stood above their long-run averages.
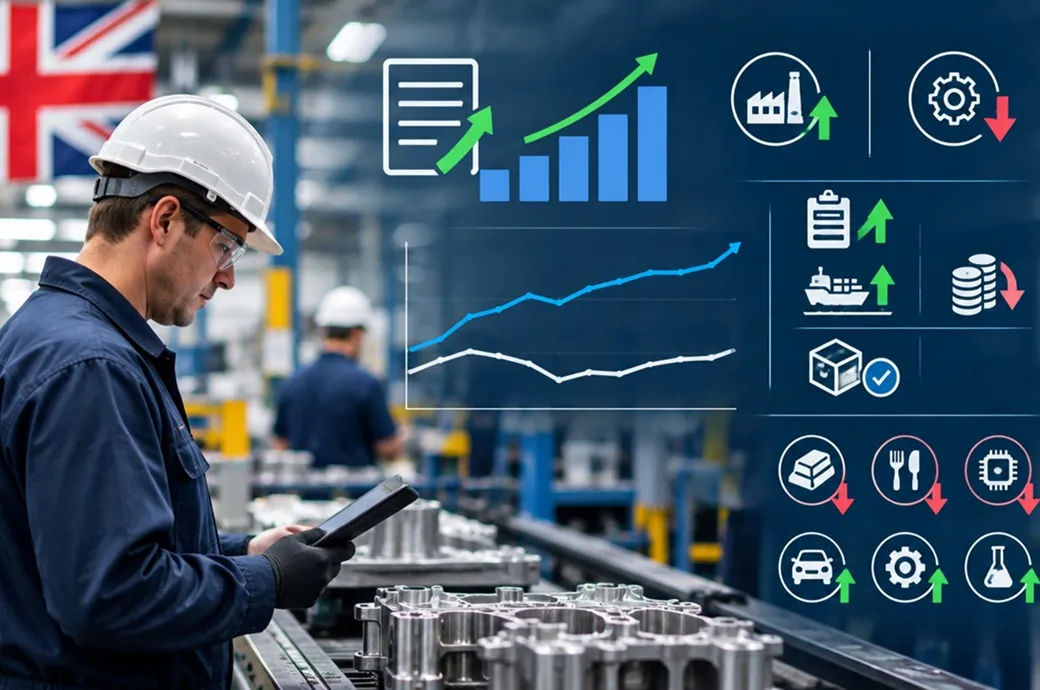
According to the CBI's latest Industrial Trends Survey, based on responses from 234 manufacturers, found output volumes fell marginally in the three months to September, with the weighted balance improving to -4 per cent from -17 per cent in the quarter to August. Manufacturers expect output volumes to fall again in the three months to December at a slow pace, with a balance of -6 per cent. Manufacturers expect output to fall only marginally in the three months to December.
The CBI survey found output decreased in 12 of 17 sub-sectors in the three months to September, driven by metal products, food, drink and tobacco, and electronic engineering. Output rose in motor vehicles and transport equipment, mechanical engineering and chemicals.
Total order books were reported as below 'normal' in September, with the balance at -9 per cent, compared with -25 per cent in August. That was above the long-run average of -14 per cent. Export order books were also below 'normal' at -9 per cent, compared with 0 per cent in August, but remained well above their long-run average of -19 per cent.
The survey also found expectations for average selling price inflation eased to +12 per cent in September from +22 per cent in August, remaining slightly above the long-run average of +8 per cent. Stocks of finished goods were reported as adequate at +2 per cent, down from +15 per cent in August, the lowest balance since April 2024 and below the long-run average of +12 per cent.
Cameron Martin, senior economist, CBI said: "There are growing signs that conditions are stabilising for manufacturers, with a marked improvement in order books for the second consecutive month - taking them to their strongest in more than three years. Output is also now falling only marginally and selling price expectations have eased considerably from the highs seen following the outbreak of conflict in the Middle East. While these are encouraging signs, it is still too early to call this a sustained recovery, with manufacturers continuing to face high supply chain, energy and employment costs. With the Budget fast approaching, government has an opportunity to build on these tentative signs of stabilisation by giving manufacturers the confidence to invest and grow. Action to remove legacy policy costs from all business electricity bills and raise the employer National Insurance Contribution secondary threshold would help turn this emerging resilience into stronger and more sustained growth."